Does Cosigning Build Credit
So, someone walked up to you and said, "Hey, will you co-sign for me?" Your brain immediately started panicking. Should you? Do you even get anything out of it? Let's dive int...
So, someone walked up to you and said, "Hey, will you co-sign for me?" Your brain immediately started panicking. Should you? Do you even get anything out of it? Let's dive into the wild world of co-signing and find out if it actually builds credit. Spoiler: things get really interesting.
What Even Is Co-Signing?
Okay, picture yourself as the sidekick in a credit movie. You're not the main character, but you're standing right there with them. Co-signing means you pledge to take on the debt if the primary borrower ghosts it.
You're basically saying, "Yup, I trust this person. A LOT." It's like being a credit wingman who refuses to leave the party early. The lender loves it because now they've got two people on the hook.
Must Read
How It Actually Works
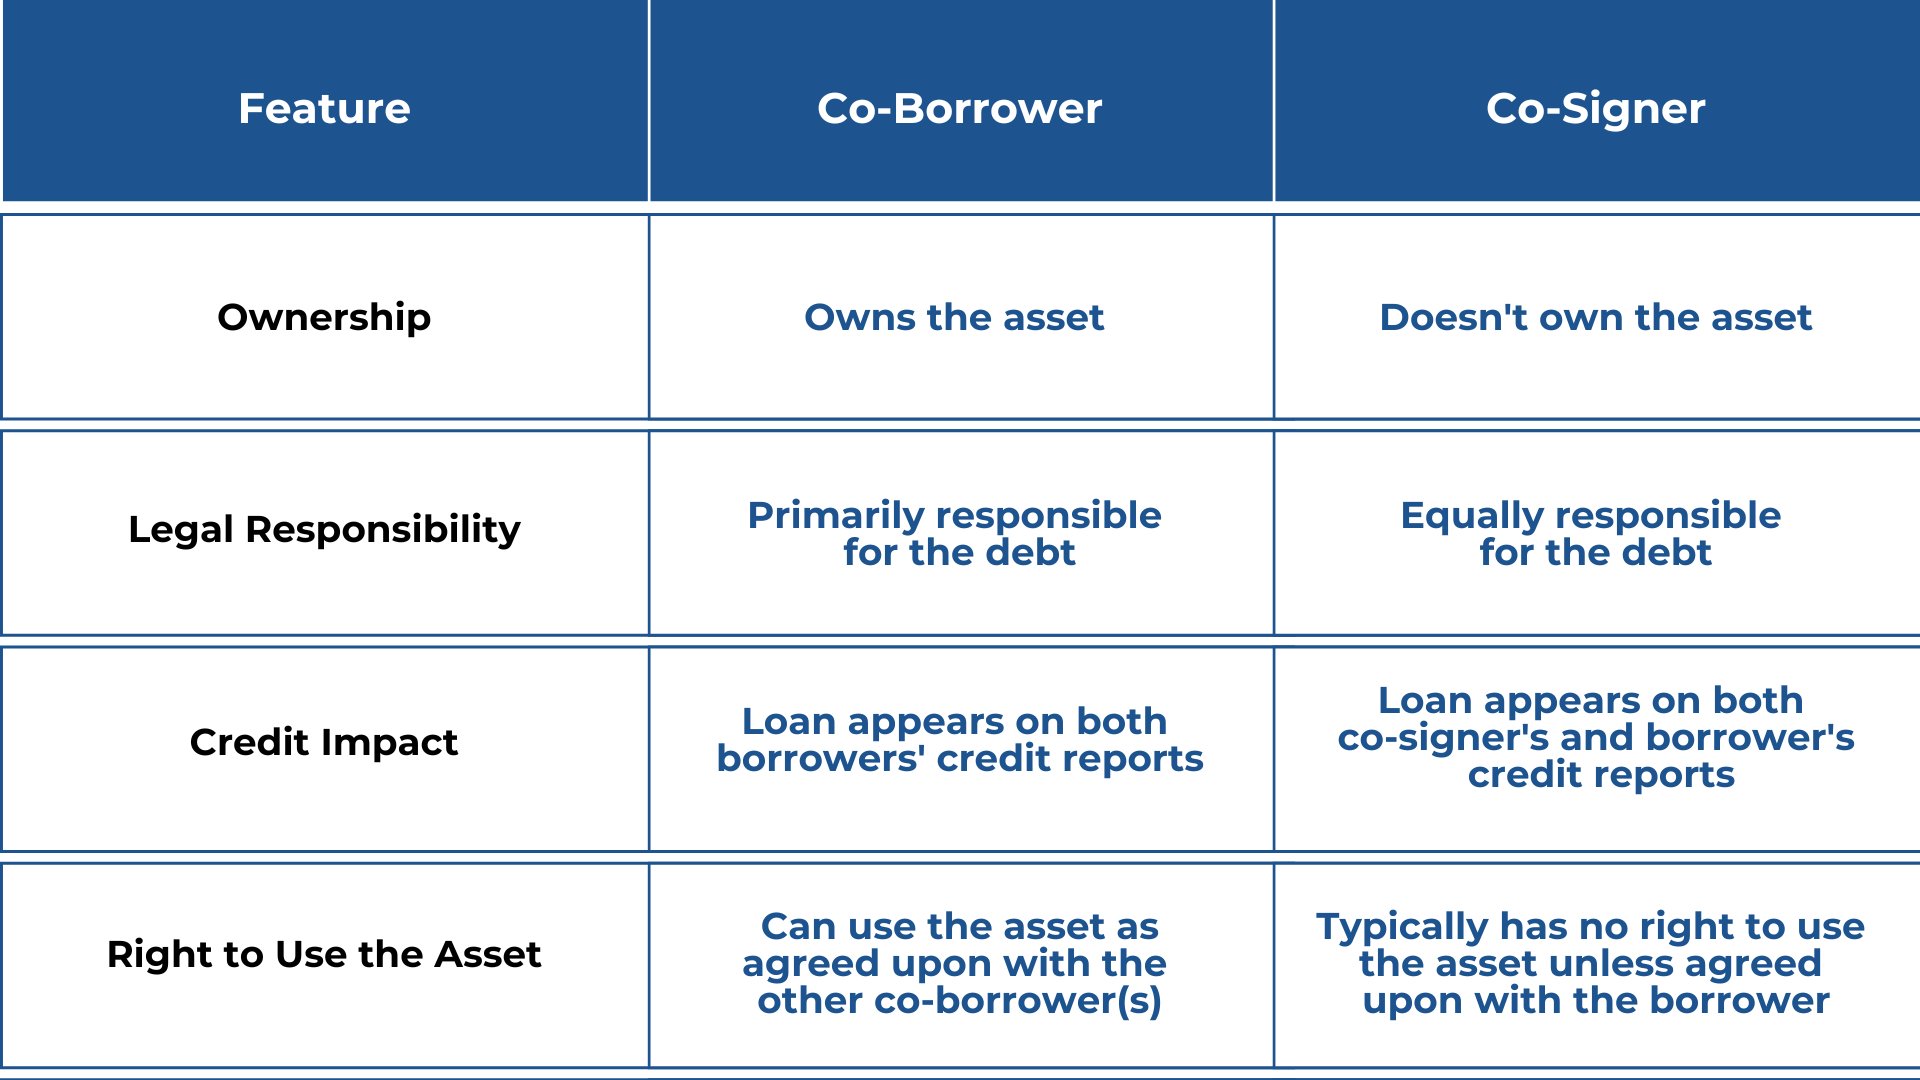
The primary borrower applies for a loan or credit card. They shake hands with the lender after you sign your life away on the dotted line. Both names appear on that account forever — well, until the debt is paid off.
Now here's the fun part. Both your credit reports will show that account. Yep, your name is attached whether you like it or not. Time to make some popcorn and watch what happens next.
Does It Build YOUR Credit?
Absolutely, yes! That co-signed account shows up on your credit report too. If payments are made on time, your score can get a nice little boost.
Think of it as a credit date night. You and your co-borrower hit up a positive payment history together. Lenders see it and think, "Wow, they're responsible."
But... It Can Backfire
Here's where it gets spicy. What if your co-borrower misses a payment? Surprise — that late mark hits YOUR credit report too. Ouch. You didn't even swipe your card.
Total balances matter as well. A high balance that you didn't even use can drag your utilization rate down. It's like carrying a backpack you didn't pack yourself.
 Best Credit Cards with Cosigner in 2024 | Credello
So yeah, co-signing CAN build credit for the primary borrower AND you. But the risk is real, folks. Co-signing without understanding the danger is like jumping off a bridge blindfolded.
Fun Facts You Didn't Know About Co-Signing
Ready for some mind-blowing trivia? Here's a quirky one: co-signing doesn't just establish new credit — it can also diversify your credit mix. A brand-new type of loan on your report? Yes, please!
Credit scoring models sometimes chase that perfect credit mix like a cat chases a laser dot. Adding a new type of debt through co-signing can nudge your score up a point or two. Tiny wins still count!
The Co-Signing Paradox
Here's the twist nobody talks about. Co-signing ages your credit history a tiny bit more. The account starts clocking in history the day it opens. That means more seasoned credit = happier scoring model.
Meanwhile, the primary borrower gets to skip years of hard work. They leapfrog right into a grown-up credit life. Meanwhile, you're sweating over their spending habits. Hilarious.
The Risk Factor Is No Joke
Alright, let's get honest for a second. Nearly 40% of co-signers experience some kind of credit damage from their arrangement. That number is staggering. Motion sickness warning because it's a roller coaster.
 How to buy a house with poor credit in Canada
You might get stuck with the full loan balance if things go sideways. Legal matters, debt collectors, and a bruised friendship? Not exactly what you signed up for. The excitement quickly wears off.
Who Should You Co-Sign For?
Your partner, maybe. Your kid? Sure. Your random friend from college who owes you a favor? Think twice. The closer the relationship, the better the odds you'll actually communicate openly.
Trust matters more than anything here. Financial, emotional, and existential trust. Because once you co-sign, you're in a mysterious love triangle with a lender and another human.
So, Should You Do It?
Only if you can afford the consequences. Only if you're prepared to occasionally nag someone about their payments. And only if you actually enjoy the idea of being financially tethered to another person.
Co-signing absolutely builds credit — for both parties involved. It's like a two-for-one deal at your favorite credit store. But like every good deal, it comes with strings attached.
So next time someone asks, take a deep breath, crunch the numbers, and maybe laugh a little. Because credit is weird, life is chaotic, and co-signing is where both collide. The adventure is on.
